What is the market overview and industry significance of the Grenade Launchers Market?
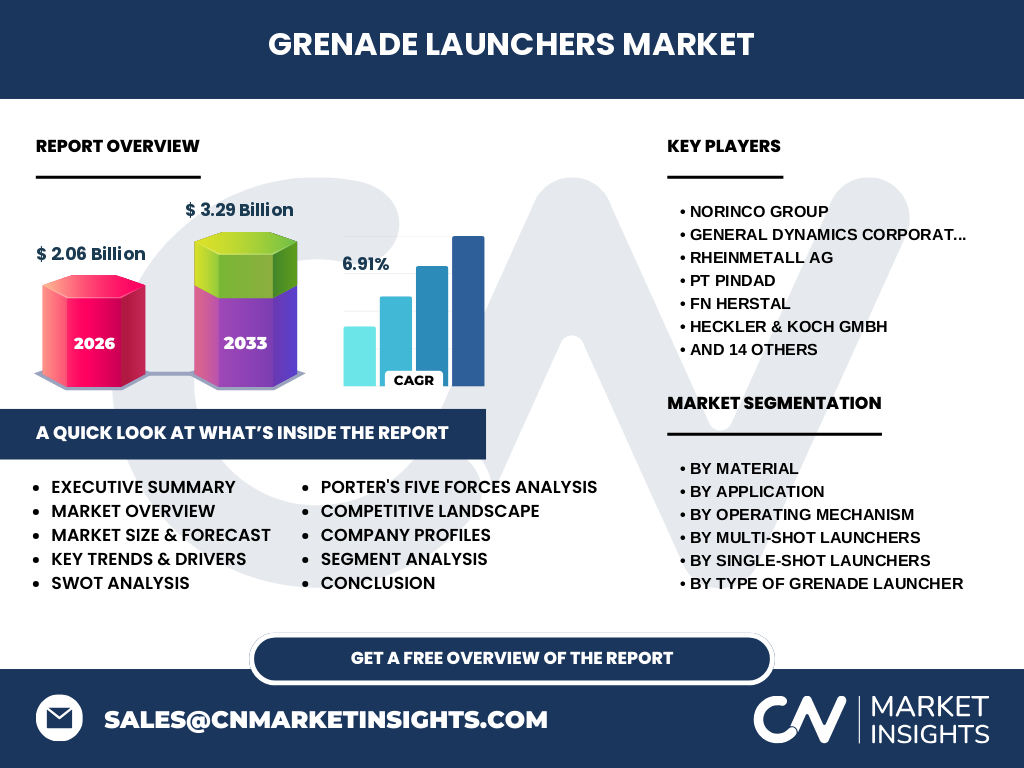
Our analysis indicates that the Grenade Launchers Market reaches a valuation of 2.06 Billion in 2026. This sector encompasses critical infantry support and vehicular armaments, governed by strict defense export controls from bodies like the Directorate General of Armaments.
Key market drivers, restraints, challenges, and opportunities shaping Grenade Launchers Market
Growth is propelled by military modernization initiatives and lightweight composite material integration. However, supply chain bottlenecks for specialty coatings and stringent ITAR regulations act as primary restraints, limiting rapid cross-border commercial transactions.
Structural Growth Trends in the Grenade Launchers Market
The shift toward programmable 40mm ammunition and smart fire-control systems is redefining infantry capabilities. Key innovators like Rheinmetall AG and Heckler & Koch GmbH are leading the integration of digital interfaces into modular weapon platforms.
How did COVID-19 impact the Grenade Launchers Market and shape recovery?
Pandemic-induced supply chain disruptions temporarily delayed procurement cycles for state-owned defense budgets. Recovery has accelerated rapidly as nations restock depleted ordnance inventories, prioritizing domestic manufacturing resilience through firms like PT Pindad.
Competitive Benchmarking and Strategic Dynamics
The market features high consolidation among tier-one defense contractors. Industry leaders such as General Dynamics Corporation and Rosoboronexport State Corporation leverage proprietary gas-operated mechanisms and robust global distribution networks to secure long-term government contracts.
Executive Summary: High-Level Synthesis of the Grenade Launchers Market
Driven by rising geopolitical tensions, our research projects the Grenade Launchers Market to expand from 2.06 Billion in 2026 to 3.29 Billion by 2033 at a 6.91% CAGR, heavily favoring automated and lightweight infantry systems.
Market Forecast and Valuation Trajectory (2027 to 2033)
Based on our econometric models, the market is poised for robust expansion, scaling from its 2026 baseline to 3.29 Billion by 2033. This growth trajectory reflects sustained defense budget allocations toward multi-shot and remote weapon station platforms.
Segmentation Analysis Across Materials, Applications, and Operating Mechanisms
The market segments by material (Metal, Polymer, Composite Materials), operating mechanism (Semi-Automatic, Fully Automatic, Gas Operation), and application (Military Use, Law Enforcement, Civilian Or Recreational Use). Composite and polymer variants dominate due to weight-reduction demands.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with North America and Asia-Pacific leading expenditure due to active military modernization. Localized constraints, such as European procurement harmonization policies, heavily influence regional manufacturing partnerships.
In-Depth Regional Review of Defense Spending
Asia-Pacific emerges as the fastest-growing region, fueled by domestic production mandates in nations like India and Singapore, involving key players such as Singapore Technologies Engineering Ltd and ST Kinetics.
Strategic Positioning of Leading Companies
Market participants like FN Herstal, Saab AB, and Israel Weapon Industries IWI focus on modularity and ergonomic enhancements. Their competitive edge stems from proprietary barrel metallurgy and advanced fire-control integration.
Porter's Five Forces Analysis of Competitive Intensity
Supplier power remains moderate due to specialized raw material requirements, while buyer power is low given that governments act as primary monopsony clients. High regulatory entry barriers protect established primes from new market entrants.
SWOT Analysis of the Global Defense Sector
Strengths include advanced recoil-reduction designs; weaknesses involve high capital expenditure requirements. Opportunities lie in smart-munition integration, while threats stem from strict international arms control treaties and geopolitical trade restrictions.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from raw alloy and polymer extraction to precision machining, subsystem integration by prime contractors like Norinco Group and Nammo AS, and final deployment by military end-users.
Investment Insights and High-Potential Areas
Investors should target developers of lightweight infantry support launchers and remote weapon station turrets. Companies integrating specialty coatings for enhanced durability present exceptional risk-adjusted growth prospects.
Conclusion and Strategic Takeaways
The Grenade Launchers Market industry trends highlight an irreversible shift toward automated, digitized firepower. Navigating compliance and investing in composite materials will dictate long-term profitability.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining defense trade registry data, primary stakeholder interviews with procurement officers, and secondary macroeconomic indicators from global defense institutes.
Scope of the Report and Coverage Parameters
This report covers global deployment dynamics across single-shot, multi-shot, and automatic launcher categories from 2026 to 2033, excluding black-market or non-state actor acquisitions due to data verification limits.
Recent Developments, Partnerships, and Product Launches
Recent strategic moves feature joint ventures between REPKON Defence and regional forces to co-produce automatic grenade launchers, alongside Ceská zbrojovka Group CZG expanding its modular weapon accessories portfolio.